
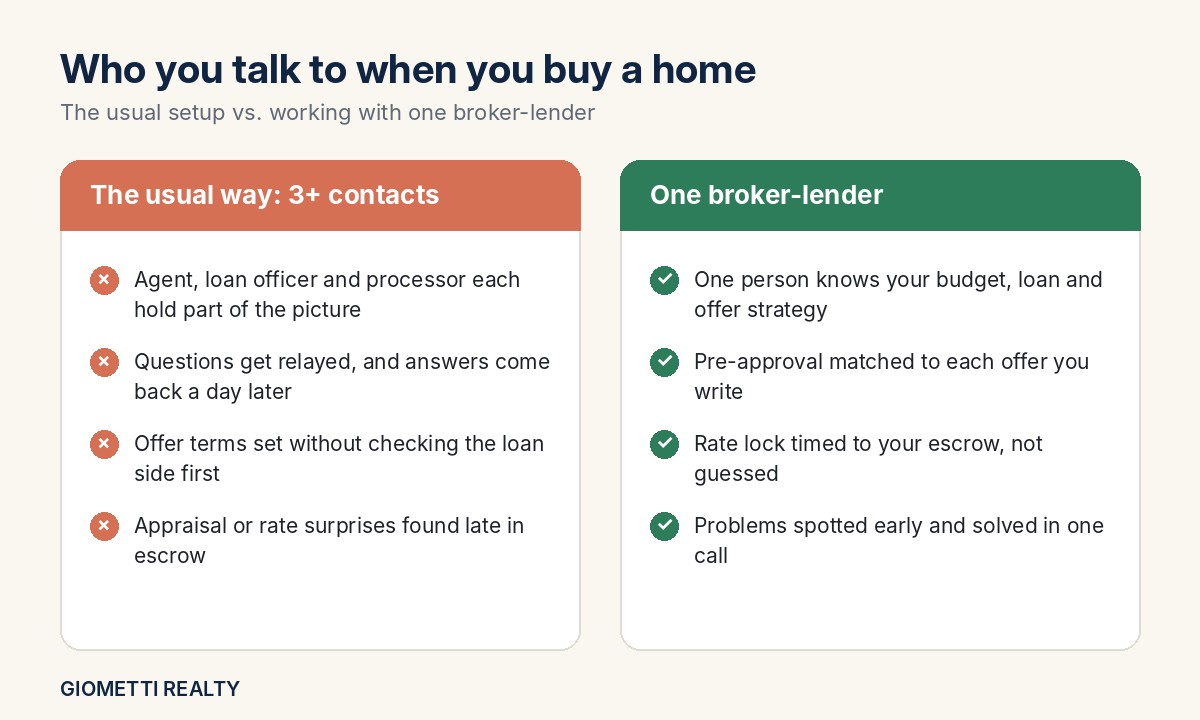
Most people buying a home in South Orange County end up managing two separate relationships at the same time: one with their real estate agent and one with their loan officer. Each one only sees part of your situation. With one broker and lender, it is just the same person doing everything from home shopping to offering on your behalf and financing your purchase. In an environment where a Mission Viejo house costs about $1.2 million and houses in the coastal communities of Dana Point and San Clemente go for over $2 million, this single contact can mean a lot to you.
I’m Danny Giometti. I’m a licensed real estate broker and a mortgage loan originator, and I was born and raised here in South OC. Below I’ll walk you through how working with one broker and lender works, the five places it saves you the most time, and when it might not be the right fit for you.
What Does It Mean to Work With a Broker and Lender in One?
A real estate broker helps you find, negotiate and buy a home. A mortgage loan originator helps you get approved for and close the loan that pays for it. Usually two different people at two different companies do these jobs, and they talk to each other mostly through you, through email chains and through the escrow officer.
When one person holds both licenses, the real estate side and the mortgage side are planned together from day one. You can check my licenses yourself: my real estate license (DRE 01916879) on the California DRE site and my mortgage license (NMLS 2116653) on NMLS Consumer Access.
5 Ways a Broker and Lender Saves You Time in South OC
1. Your Pre-Approval Matches Your Actual Offer
Sellers and listing agents in Laguna Niguel and San Clemente want to see a pre-approval letter that fits the offer in front of them. If you offer $1,550,000 with 20% down, a letter that says “approved up to $1.7 million” makes listing agents wonder whether your lender actually ran the numbers.
Because I write both the offer and the letter, I can issue an updated letter for the exact price and terms the same evening, without waiting for a loan officer to call back. When three buyers are competing for the same home, that speed matters.
2. Offer Terms Are Built Around Your Loan
Contingency periods, the close-of-escrow date and how much you can cover if the appraisal comes in low all depend on your loan. When your agent writes an offer without knowing your loan details, the terms are a guess. Then you have to ask for an extension later, and that weakens your position with the seller.
Working with one mortgage broker and real estate agent means every term in your offer is checked against your financing before it goes out. If a 21-day close is realistic for your loan, I’ll write 21 days. If it isn’t, I won’t promise it.
3. Rate Locks Are Timed to Your Escrow
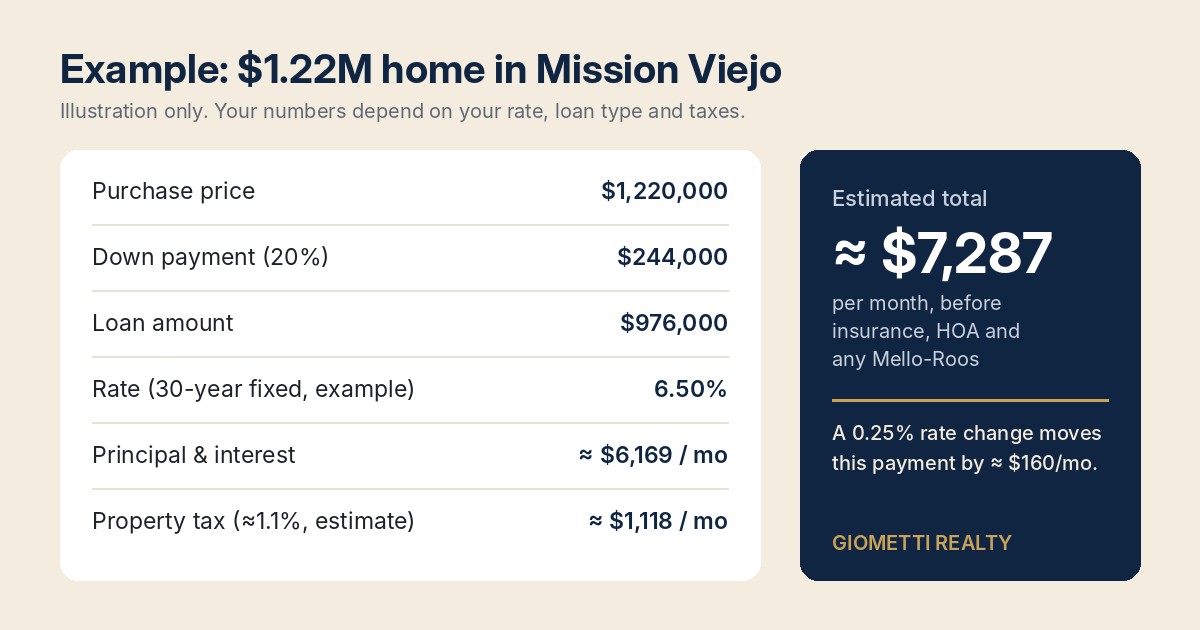
Rates are in the mid-6% range right now, according to Freddie Mac’s Primary Mortgage Market Survey, so the timing of your rate lock affects your monthly payment. If you lock too early, your lock can expire before you close. If you lock too late, you’re exposed to any rate increase in between.
Since I’m managing your escrow timeline too, I know when inspections clear, when the appraisal is scheduled and when your closing date is firm. That lets me time your lock to the real deal instead of guessing.
4. Problems Get Solved in One Call
Say the appraisal comes in low, the underwriter asks for another bank statement, or the inspection shows a roof issue that could affect your loan. In the usual setup, your agent hears about it from you and your lender hears about it from escrow. Then everyone waits for a call back.
With a broker and lender in one, the person who spots the problem is the same person who can fix it. I can negotiate a credit with the seller and adjust your loan in the same afternoon. Older homes in Mission Viejo and San Juan Capistrano often turn up sewer line or permit questions, so this comes up more often than people expect. (That’s also why I recommend a sewer inspection. My list of South OC businesses I trust includes a plumber I send clients to.)
5. You Only Explain Your Situation Once
A self-employed income, going up market from a home you currently own, money gifted to you by your family, and an ADU that you plan on renting out; all of these affect both your home buying journey and your mortgage. Because of their individual advantages, you end up explaining things twice.
Through me, you explain things only once. I use this same image for my neighborhood selection process and offer writing and structuring your mortgage.

Separate Agent/Loan Officer vs. One Broker/Lender
| Step | Separate agent and lender | One broker and lender |
|---|---|---|
| Pre-approval letter | Requested from lender, often next day | Updated for each offer, same day |
| Offer terms | Written without full loan details | Checked against your loan before sending |
| Rate lock | Timed by lender, separate from escrow | Timed to your actual escrow dates |
| Appraisal or underwriting issue | Passed between two offices | Handled by one person in one call |
| Who you call | Two or three people | One person |
Is a Broker-Lender Right for Every Buyer?
Not always. Here’s how to decide:
- Compare offers anyway. You’re never required to use me as your lender. Ask for a Loan Estimate and compare it with other lenders. I’ll gladly go through it with you line by line.
- You’ll see in writing how I’m paid. You’ll get disclosures that show how I’m paid on the real estate side and on the loan side, so nothing is hidden.
- Some loans need a specialist. If you need a very specific program, I’ll tell you up front and point you to the right person.
For most buyers I work with in Mission Viejo, Laguna Niguel, Dana Point and San Clemente, having one person handle both sides means fewer surprises and a faster, calmer escrow. To see how each city is moving right now, read my South Orange County real estate market update.
How a Broker and Lender Helps in Each South OC City
Every South Orange County city moves a little differently, and those differences affect your offer and your loan. These numbers come from my mid-September 2026 market update.
Mission Viejo
Median prices are running around $1.20 to $1.24 million. Homes sell in about 40 to 50 days, at 99 to 100 percent of list price. Since sellers are getting close to asking, your offer has to look clean and solid. A pre-approval letter written for your exact price and down payment does a lot of the work here. Many Mission Viejo homes were built in the 1970s and 1980s, so I plan the inspection period and repair credits together with your loan from the start.
Laguna Niguel
Median prices range from $1.5 million to $1.6 million, with houses being sold at the upper end of the 30s in days on market. Demand has remained consistent, so good properties do not linger for very long. Home buyers in this community are usually trading up from condominiums or smaller homes. If you are buying and selling a property with the same escrow, the timing becomes much more efficient.
Dana Point
The median prices range from $2.1 to $2.2 million, and properties are selling in a period between 45 and 60 days or even longer; also, price reductions are getting more frequent. This allows for more bargaining on the part of buyers. Given that the prices at this point require financing through a jumbo loan, the requirements in terms of reserves and paperwork are strict. I know exactly what your loan requirements are, and therefore, I can bargain harder.
San Clemente
The median is near $2.1 million, but homes are selling faster than in Dana Point, in the low to mid 30s for days on market. Newer communities like Talega often carry Mello-Roos taxes and HOA dues. I include those in your real monthly payment before we write an offer, so there are no surprises later.
San Juan Capistrano
Prices range widely, from about $1 million to over $2 million, depending on the neighborhood and lot. Some properties come with horse-zoning, larger lots or older additions. Those can raise appraisal and permit questions that are much easier to handle when your agent and your lender are the same person.
What to Have Ready for a South OC Pre-Approval
The faster I have your documents, the faster I can issue a strong pre-approval. Here’s what most buyers need:
- Income: your last 30 days of pay stubs and two years of W-2s. If you’re self-employed, two years of personal and business tax returns.
- Assets: two months of bank and investment statements, showing your down payment and reserves.
- Gift funds: if family is helping with the down payment, a signed gift letter and a record of the transfer.
- Current home: if you’re selling to buy, your current mortgage statement and an idea of your expected sale price.
- ID and credit: a valid photo ID and permission to pull your credit.
Working with one broker and lender means you send these documents once. I use the same file to set your budget, choose the right loan and write your offers.
Common Mistakes That Slow Down a South OC Purchase
Most delays I see could have been avoided with a little planning. These are the most common:
- Shopping before you’re pre-approved. Falling for a home before you know your real budget leads to rushed decisions or offers that fall apart.
- Making big purchases during escrow. A new car loan or a large credit card charge can change your approval right before closing.
- Getting insurance quotes too late. Homeowners insurance has become harder to get in parts of California. I recommend getting quotes as soon as your offer is accepted.
- Ignoring HOA and Mello-Roos costs. These can add hundreds of dollars a month and affect how much you qualify for.
- Moving money around without records. Large deposits or transfers need a paper trail. Talk to me before you move funds for your down payment.
When your agent and your lender are the same person, these issues are caught early, because one person is watching both the deal and the loan the whole time.
Questions to Ask Before Choosing a Broker and Lender
Not every agent who offers loans works the same way. Before you commit, ask these questions. A good broker-lender will answer them clearly and won’t mind that you asked.
Are you licensed for both real estate and mortgages?
Ask for both license numbers, a DRE number for real estate and an NMLS number for lending, and look them up yourself. You can check the real estate license on the California DRE website and the mortgage license on NMLS Consumer Access. Both should be active and in good standing.
Do you handle the loan yourself, or pass it to someone else?
Some agents refer your loan to a partner company and call it “in-house.” That isn’t the same thing. If someone else is running your loan, you’re back to two people and two timelines. Ask who will actually order your appraisal, talk to underwriting and lock your rate.
How will I know what you’re being compensated for?
You need to be given clear and documented information about the payment structure of your broker-lender in real estate and loan aspects. The Loan Estimate details the loan fees while your purchase documentation details the commission. Any compensation structures that seem unclear to you should be clarified by asking.
What kinds of loans do you offer?
For South Orange County buyers, there are usually two kinds of mortgages available: conventional or high-balance and jumbo. There are others who will require VA, FHA, and bank statement loans for self-employed individuals. It is important that you work with someone who can provide you with your kind of mortgage.
How quickly can you update a pre-approval letter?
In a competitive market, you may write several offers before one is accepted. Ask how fast you can get a new letter matched to each price. With a true broker-lender, the answer should be the same day, often within the hour.
Buy and Sell at the Same Time in South OC
Most of my buyers have an existing home in Mission Viejo, Laguna Niguel or Rancho Santa Margarita that they wish to upgrade, move towards the coast or scale down on. This translates into two escrows, two sets of deadlines and a loan that will depend on the sale of your first home.
This is why it pays to have one realtor and lender. I can help you value your current home, arrange for your new loan using the proceeds of your sale, and schedule both closing dates such that you will not end up making payments for two mortgages or having to move twice. If you are buying before selling, I will be able to discuss all the possible solutions including bridge financing and rent back from your buyer and the effects each has on your qualifications.
One realtor handles both transactions, giving you only one timeline, plan and contact person.
Frequently Asked Questions
Can my real estate agent also be my mortgage lender in California?
Yes. In California, one person can act as both if they hold a real estate broker or salesperson license from the DRE and a mortgage loan originator license through the NMLS. You should receive written disclosures explaining how they are paid on each side.
Does using one broker and lender cost more?
Not necessarily. You still receive a standard Loan Estimate, so you can compare rates and fees with any other lender before you commit. You are never required to use the same person for both.
How quickly can I be pre-approved in South Orange County?
With your income, asset, and credit paperwork complete, it’s possible to obtain your pre-approval in a day or two. If you go with a broker lender, your pre-approval can even be refreshed to reflect the terms of your offer on that very day.
Is a broker lender right for first-time home buyers?
Many times, yes. Since first-time home buyers are usually the ones who have the most questions about how everything fits into place, it becomes easier to have one single point of contact explain everything.
What areas of South OC does Giometti Realty work in?
Giometti Realty helps buyers and sellers across South Orange County, including Mission Viejo, Laguna Niguel, Dana Point, San Clemente, San Juan Capistrano and Laguna Beach.
Ready to Buy With One Point of Contact?
If you’re thinking about buying in South Orange County, let’s start with a quick conversation about your budget, your timeline and the neighborhoods you’re considering. I’ll show you what you’d likely qualify for and how we’d structure your offer, all in one meeting.
Call or Text (949) 422-5750 Email Danny
Daniel Giometti, Broker & Mortgage Loan Originator. Giometti Realty Inc. DRE 01916879 | Corp DRE 0218039 | NMLS 2116653. Payment examples are for illustration only and are not a commitment to lend. Rates, terms and approval depend on credit, income, property and market conditions. Equal Housing Opportunity.